
Setting up a sole trader business in the UK is straightforward.
You can begin trading under your own name or a chosen business name, keep records of your income and expenses, and register for Self Assessment with HM Revenue and Customs (HMRC) when required. You do not need to register a company with Companies House.
To set up a sole trader business, you need to choose your business activity, decide on a trading name, check whether you need to register with HMRC, organise your finances and understand your tax responsibilities.
Registration with HMRC is free, although running the business may involve additional costs.
This guide explains the registration process, startup expenses, tax rules, legal responsibilities and common mistakes to avoid.
What Does It Mean to Operate as a Sole Trader in the UK?
A sole trader is an individual who owns and operates a business in their own name or under a trading name.
It is one of the simplest business structures in the UK because it involves fewer administrative requirements than running a limited company.
As a sole trader, you control the business, make decisions independently and keep the profits after paying any tax due. However, you are personally responsible for business debts and legal obligations.
This means your personal finances and business finances are not legally separate. If the business cannot repay its debts, your personal assets could be at risk.
Sole trading is commonly used by freelancers, consultants, tradespeople, online sellers and people starting small businesses.
For example, a freelance graphic designer can work directly with clients, issue invoices and manage business expenses without establishing a limited company.
Although every sole trader is self-employed for tax purposes, not every person working independently is necessarily a sole trader. Individual business partners are also self-employed, while limited-company directors have a different legal and tax position.
What Are the Requirements to Become a Sole Trader?
Before starting, you should understand the basic eligibility requirements and gather the information needed for HMRC registration.
Eligibility Requirements
Most people who are legally permitted to work for themselves in the UK can operate as sole traders.
You should check the following:
- Right to Work: Ensure Your Immigration Status Permits Self-Employment in the UK
- Business Activity: Identify the Products or Services You Intend to Offer
- Tax Responsibilities: Understand When Self Assessment Registration Is Required
- Legal Requirements: Check Whether Your Business Needs Licences, Permits or Insurance
- Financial Planning: Estimate Your Initial Costs and Expected Business Income
You can also operate as a sole trader while working as an employee, provided your employment contract and any applicable restrictions allow it.
Documents and Information Required
When registering with HMRC, you will generally need:
- National Insurance Number: Your Personal National Insurance Number
- Personal Details: Your Name, Address and Date of Birth
- Business Information: Your Business Activity and Trading Name, If Applicable
- Trading Start Date: The Date You Started Working for Yourself
- HMRC Account Details: Your Existing Sign-In Details, If You Already Have an Account
The precise information required depends on whether you have previously registered for Self Assessment.
Choosing a Business Name
You can trade using your personal name or choose a separate business name.
For example, someone called James Wilson could operate as “James Wilson” or use a trading name such as “Wilson Digital Services”.
However, sole traders cannot use names that falsely suggest limited-company status. Names must not include terms such as “Limited”, “Ltd”, “LLP” or “plc”.
You should also check for existing trademarks and avoid names that could create legal disputes.
A suitable name should be memorable, relevant to your services and easy for customers to recognise. Understanding how to come up with a business name can help you choose an identity that supports future growth.
How to Register as a Sole Trader With HMRC?
You register as a sole trader through Self Assessment rather than Companies House. HMRC provides an online service that guides you through the appropriate registration process.
Step 1: Create or Sign In to Your HMRC Online Account
Visit the official GOV.UK sole trader registration page and follow the instructions.
If you already have an HMRC account, you may be able to use your existing sign-in details. New users will be guided through the relevant account setup.
The process depends on whether you have previously registered for Self Assessment and whether you need to reactivate an existing record.
Step 2: Register for Self Assessment
HMRC uses Self Assessment to collect information about income that is not automatically taxed through PAYE.
Choose the appropriate registration route for someone who is self-employed as a sole trader.
If you have already registered for Self Assessment for another reason, make sure HMRC also records your self-employment correctly.
Step 3: Provide Your Personal and Business Details
Complete the required information accurately.
You may be asked for your National Insurance number, business activity, trading name and the date your self-employment began.
Check the details before submitting the application. Incorrect information could delay registration or cause problems with your tax records.
Step 4: Receive Your Unique Taxpayer Reference (UTR)
After successful registration, HMRC provides a Unique Taxpayer Reference, commonly called a UTR.
This is a ten-digit reference used to identify your Self Assessment tax record.
The time required to receive it varies according to the registration method and HMRC processing times. You can check the progress of your registration through HMRC’s official services.
Step 5: Maintain Business Records and Meet Tax Deadlines
Once registered, keep accurate records of your business income, expenses, invoices and receipts.
You will generally need to submit a Self Assessment tax return each year unless HMRC confirms that you no longer need to do so.
Registration alone does not complete your ongoing tax obligations.
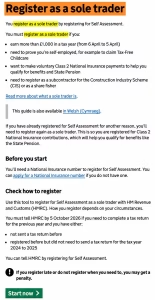
Official GOV.UK guidance showing when sole traders must register for Self Assessment and how to begin the registration process.
When Do You Need to Register as a Sole Trader?
You can generally begin trading before registering with HMRC. However, registration becomes compulsory once you meet the relevant requirements.
£1,000 Trading Income Threshold
You normally need to register as a sole trader if your gross self-employment income exceeds £1,000 during a tax year.
Gross income means the total amount received before deducting business expenses.
For example:
| Business Income | Business Expenses | Registration Position |
| £800 | £200 | Normally Not Required Solely Because of Trading Income |
| £1,200 | £500 | Registration Normally Required |
| £5,000 | £2,000 | Registration Normally Required |
The £1,000 threshold relates to trading income, not profit.
You may also need to register below this threshold if you must prove self-employment, wish to pay voluntary Class 2 National Insurance or have certain other obligations.
HMRC Registration Deadlines
You usually need to notify HMRC by 5 October following the end of the tax year in which your registration obligation arose.
For example, someone who starts trading during the 2026/27 tax year and needs to register should normally do so by 5 October 2027.
For the 2025/26 tax year, the usual registration deadline was 5 October 2026.
The standard online Self Assessment submission and payment deadline for 2025/26 is 31 January 2027.
Missing registration or tax deadlines can result in penalties, depending on the circumstances.
How Much Does It Cost to Start a Sole Trader Business?
Registering as a sole trader with HMRC is free. There is no Companies House incorporation fee because a sole trader is not a separate limited company.
However, the actual cost of starting your business depends on the industry, equipment and services required.
| Startup Expense | Typical Cost Consideration |
| HMRC Registration | Free |
| Business Bank Account | Free or Paid, Depending on Provider |
| Accounting Software | Free or Subscription-Based |
| Business Insurance | Depends on Occupation and Cover |
| Website and Domain | Depends on Provider and Requirements |
| Licences and Permits | Depends on Business Activity |
| Equipment and Materials | Depends on Type of Business |
For example, a freelance writer working from home may need little more than an existing computer and an internet connection.
A mobile catering business may face significantly higher costs for equipment, food safety compliance, insurance and suitable premises.
Before spending money, calculate your expected running costs and consider writing a business plan to estimate income, expenses and cash flow.
Do You Need a Business Bank Account?
Sole traders are not legally required to open a separate business bank account.
However, keeping personal and business transactions separate makes accounting easier and helps you identify taxable income and allowable expenses.
Some personal bank accounts prohibit business transactions, so check your provider’s terms before using an existing account.
What Taxes Do Sole Traders Pay in the UK?
Sole traders may need to pay Income Tax, National Insurance contributions and VAT, depending on their profits and business activities.
Income Tax Rates and Personal Allowance
Sole traders generally pay Income Tax on taxable business profits rather than total sales.
Taxable profit is calculated by deducting allowable business expenses from business income, subject to the applicable tax rules.
For the 2026/27 tax year, the standard Personal Allowance is £12,570.
The main Income Tax bands for England, Wales and Northern Ireland are:
| Annual Taxable Income Including Personal Allowance | Income Tax Rate |
| Up to £12,570 | 0% |
| £12,571 to £50,270 | 20% |
| £50,271 to £125,140 | 40% |
| Above £125,140 | 45% |
The Personal Allowance reduces when adjusted net income exceeds £100,000. Scotland has different Income Tax bands for non-savings income.
Example: If a sole trader earns £20,000 in sales and has £5,000 in allowable business expenses, their profit is £15,000.
Assuming they have no other taxable income, receive the full Personal Allowance and pay the basic rate of Income Tax, the illustrative calculation is:
- Business Income: £20,000
- Allowable Expenses: £5,000
- Taxable Profit Before Personal Allowance: £15,000
- Personal Allowance: £12,570
- Income Subject to Income Tax: £2,430
- Income Tax at 20%: £486
Class 4 National Insurance would also be £145.80, making the combined illustrative liability £631.80 before any other adjustments.
Class 2 and Class 4 National Insurance
The National Insurance rules for self-employed people depend on annual profits.
For 2026/27:
- Class 2 National Insurance: Generally Treated as Paid When Annual Profits Reach £7,105, Without a Separate Compulsory Payment
- Voluntary Class 2 Contributions: £3.65 Per Week Where Eligible
- Class 4 National Insurance: 6% on Profits Above £12,570 up to £50,270
- Additional Class 4 Rate: 2% on Profits Above £50,270
These contributions are separate from Income Tax, although Class 4 is generally calculated through Self Assessment.
VAT Registration Threshold
You must generally register for VAT if your taxable turnover exceeds £90,000 over the previous rolling 12 months.
Registration is also required if you expect taxable turnover to exceed £90,000 in the next 30 days alone.
Businesses below the threshold may choose voluntary VAT registration. Other rules can apply, including to businesses established outside the UK.
Making Tax Digital Requirements
Making Tax Digital for Income Tax is being introduced in stages for qualifying sole traders and landlords.
| Start Date | Qualifying Income Threshold |
| 6 April 2026 | Over £50,000 Based on 2024/25 Income |
| 6 April 2027 | Over £30,000 Based on 2025/26 Income |
| 6 April 2028 | Over £20,000 Based on 2026/27 Income |
Qualifying income generally means combined gross self-employment and property income before deducting expenses.
People within the requirements must use compatible software to maintain digital records and send quarterly updates to HMRC, subject to exemptions and other eligibility conditions.
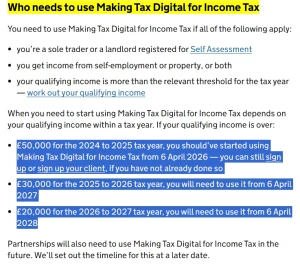
Official HMRC guidance confirming the phased Making Tax Digital introduction dates and qualifying income thresholds for sole traders.
What Are the Legal and Financial Responsibilities of a Sole Trader?
Registering with HMRC is only one part of running a sole trader business. You must also manage financial records, comply with relevant regulations and submit tax information when required.
Keeping Accurate Financial Records
You should maintain reliable records of:
- Business Income: Payments Received From Customers and Clients
- Business Expenses: Purchases and Operating Costs
- Sales Invoices: Documents Issued for Goods and Services
- Receipts: Evidence of Business Purchases
- Bank Statements: Records Supporting Business Transactions
Self-employed business records generally need to be retained for at least five years after the relevant 31 January tax return deadline.
Filing Self Assessment Tax Returns
Sole traders who are required to complete Self Assessment must report their income and allowable expenses.
For the 2025/26 tax year, the standard online filing and payment deadline is 31 January 2027.
Some taxpayers must also make payments on account towards the following year’s tax bill, usually due on 31 January and 31 July.
Setting money aside regularly can help prevent cash-flow difficulties when a tax payment becomes due.
Claiming Allowable Business Expenses
Allowable business expenses can reduce your taxable profit.
Common examples include:
- Office Costs: Stationery, Telephone Bills and Business Software
- Travel Expenses: Eligible Business Travel and Transport Costs
- Marketing Expenses: Advertising, Website Costs and Promotions
- Professional Fees: Business-Related Accounting and Legal Services
- Equipment Costs: Eligible Tools, Computers and Machinery
Personal expenses cannot generally be claimed as business expenses.
You also cannot claim actual business expenses in addition to the £1,000 trading allowance for the same income.
Business Licences and Insurance
Some businesses require additional permissions before they can legally operate.
For example, food businesses may need to register with their local authority, while certain trades require specific licences or professional qualifications.
Public liability and professional indemnity insurance may be useful depending on the risks involved.
Employer’s liability insurance is generally required when you employ staff, subject to specific exceptions.
What Are the Advantages and Disadvantages of Being a Sole Trader?
Operating as a sole trader offers simplicity and independence, but it also carries financial and legal risks.
| Advantages | Disadvantages |
| Free HMRC Registration | Unlimited Personal Liability |
| Simple Business Structure | Personally Responsible for Business Debts |
| Complete Control Over Decisions | No Separate Legal Identity |
| Fewer Company Filing Requirements | May Be Harder to Raise Equity Investment |
| Keep Profits After Tax | Responsible for Managing Tax and Administration |
| Flexible Business Operations | Income May Be Less Predictable |
A sole trader structure may suit someone testing a business idea, offering freelance services or operating a relatively low-risk business.
However, someone entering substantial contracts, employing several workers or seeking external investment may need to consider a different structure.
Sole Trader vs Limited Company: Which Is Better?
The main difference is that a sole trader and their business are legally the same person, whereas a limited company has a separate legal identity.
| Feature | Sole Trader | Limited Company |
| Legal Identity | Individual | Separate Legal Entity |
| Registration | HMRC When Required | Companies House |
| Liability | Unlimited | Generally Limited |
| Main Business Taxes | Income Tax and National Insurance | Corporation Tax |
| Administrative Requirements | Generally Simpler | More Extensive |
| Public Financial Filings | No Company Accounts | Company Filing Requirements Apply |
| Ownership | Individual Owner | Shareholders |
A sole trader may be more suitable when starting a small operation with limited costs and relatively straightforward financial arrangements.
A limited company may be worth considering when personal liability, investment, ownership arrangements or business growth become more significant.
However, limited liability does not remove every personal risk, particularly where directors provide personal guarantees or breach legal duties.
Entrepreneurs considering incorporation should understand how to register a company in the UK before deciding whether the additional legal and accounting responsibilities are worthwhile.
What Are the Common Mistakes to Avoid When Starting as a Sole Trader?
Although setting up as a sole trader is relatively simple, certain mistakes can create financial problems or unnecessary administrative work.
The most common mistakes include:
- Missing HMRC Deadlines: Registering Late or Failing to Submit Required Tax Returns
- Confusing Revenue With Profit: Assuming Tax Is Calculated on Total Sales Without Considering Allowable Expenses
- Mixing Business and Personal Transactions: Making It Difficult to Track Business Finances
- Ignoring Tax Liabilities: Spending Earnings Without Budgeting for Future Payments
- Failing to Keep Records: Losing Invoices, Receipts or Evidence of Business Expenses
- Overlooking Legal Requirements: Operating Without Necessary Licences or Insurance
- Ignoring Business Planning: Starting Without Understanding Costs, Customers or Cash Flow
For example, someone earning £3,000 per month from freelance work should not assume that the entire amount is available for personal spending.
Business expenses, tax, National Insurance and possible advance tax payments all need to be considered.
Learning how to run a business successfully can also help sole traders improve financial planning, customer management and long-term sustainability.
Conclusion
Setting up a sole trader business in the UK is one of the simplest ways to begin self-employment. You can start trading without forming a limited company, register with HMRC when required and maintain direct control over your business.
However, successful sole trading involves more than completing a registration form. Understanding tax obligations, keeping accurate records, managing costs and complying with legal requirements are essential.
Before starting, confirm that the structure suits your business activities, estimate your expenses and check the relevant HMRC deadlines. With proper preparation, sole trading can provide a flexible foundation for building and growing a business.
Frequently Asked Questions
Can I Start a Sole Trader Business Without Registering With HMRC?
Yes. You can generally start trading before registering, but you normally must register if gross self-employment income exceeds £1,000 in a tax year or another registration requirement applies.
Is It Free to Register as a Sole Trader?
Yes. Registering as a sole trader through HMRC is free, although insurance, software, equipment and other operating expenses may involve costs.
How Long Does It Take to Become a Sole Trader?
You can usually begin trading immediately, but completing HMRC registration and receiving your UTR can take additional time depending on your circumstances.
Do I Need a Business Bank Account as a Sole Trader?
No. A separate business bank account is not legally compulsory, but it can simplify accounting. Check whether your personal bank allows business transactions.
Can I Be Employed and Self-Employed at the Same Time?
Yes. You can work as an employee and operate a sole trader business, provided your employment conditions permit it and you meet the relevant tax obligations.
What Happens If I Do Not Register as a Sole Trader?
If registration is required and you miss the deadline, HMRC may impose penalties. Register as soon as possible and address any outstanding tax obligations.
Can I Change From a Sole Trader to a Limited Company Later?
Yes. You can establish a limited company and transfer business activities where appropriate, but you must follow the relevant tax, contractual and registration procedures.